What is the scope and industry significance of the Space Tourism Market?
Our analysis indicates that the Space Tourism Market represents a paradigm shift in aerospace logistics, valued at 1.40 Billion in 2026. This sector transforms governmental spaceflight into a commercial asset, driven by private launch providers navigating FAA and ICAO regulatory frameworks.
Structural Growth Drivers and Market Restraints
The data suggests rapid acceleration fueled by reusable rocket technology and high-net-worth demand. However, structural constraints persist, including carbon-composite supply chain bottlenecks and stringent planetary protection protocols enforced by bodies like NASA and international aviation authorities.
Emerging Trends in Commercial Spaceflight
The shift toward private astronaut missions and sustained microgravity research defines current industry trends. Innovators are prioritizing commercial space station integration over short sub-orbital hops, creating new revenue streams for orbital habitats.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced supply chain disruptions temporarily delayed avionics procurement and ground-facility construction. Despite these hurdles, post-pandemic capital influx from private equity accelerated test flight cadences for key market participants.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high market concentration dominated by pioneers like Space Exploration Technologies Corp and Blue Origin Enterprises LP. These firms leverage proprietary vertical integration to outpace legacy aerospace contractors.
Executive Summary of the Space Tourism Market
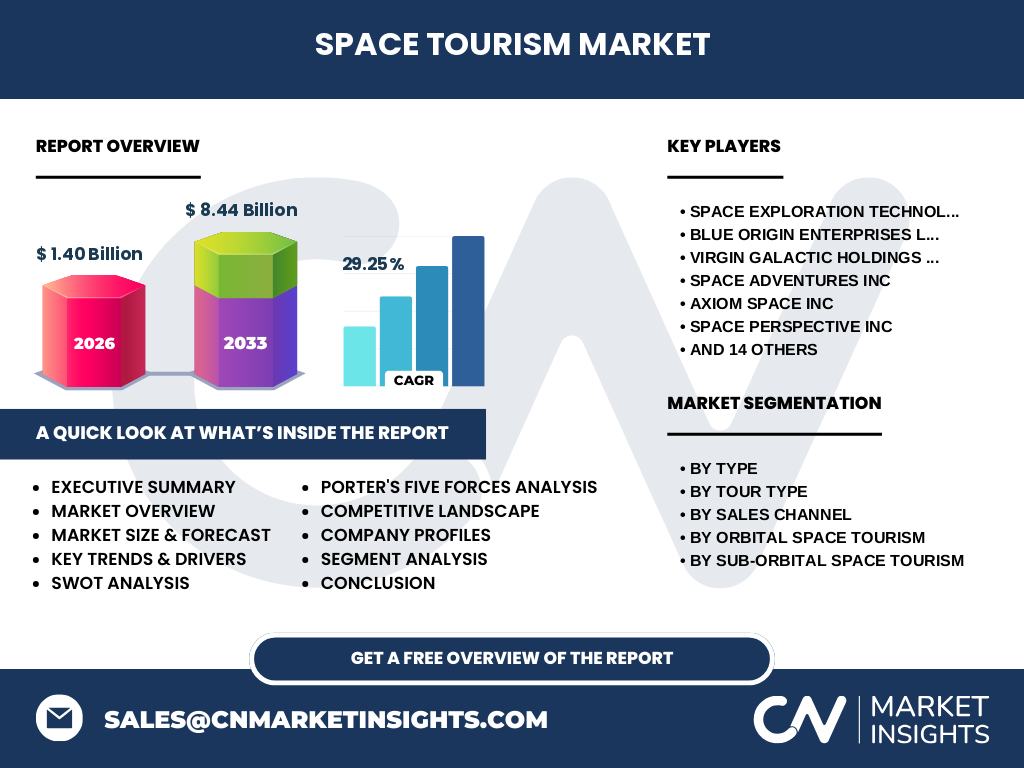
Our research confirms a booming commercial frontier, projecting the market to surge from 1.40 Billion in 2026 to 8.44 Billion by 2033 at a 29.25% CAGR, driven by technological maturation and expanding private infrastructure.
Space Tourism Market Forecast (2027 to 2033)
Based on our econometric models, the market will achieve a phenomenal 29.25% CAGR, scaling from 1.40 Billion to 8.44 Billion. This trajectory depends on the scaling of orbital habitats and reliable crewed vehicle turnaround times.
Segmentation Analysis: Types and Sales Channels
The market bifurcates into Sub-Orbital and Orbital Space Tourism, catering to Individual Travel and Professional Groups. Sales are split between direct Launch Provider bookings and Third Party Partnership brokerages managing luxury clientele.
Regional Market Analysis and Geographic Distribution
North America commands market leadership due to established launch infrastructure at Kennedy Space Center and private spaceports. Meanwhile, Asia-Pacific emerges as a high-potential growth region driven by burgeoning private aerospace investments.
In-Depth Regional Review of Launch Hubs
United States facilities dominate flight operations, whereas emerging European spaceports focus on sustainable propulsion and balloon-borne edge-of-space concepts. Regulatory harmonization remains a critical hurdle for cross-border passenger transit.
Company Profiles and Market Positioning
Industry leaders occupy distinct niches: Virgin Galactic Holdings Inc focuses on rocket-powered sub-orbital planes, Axiom Space Inc targets commercial space station integration, and Space Perspective Inc champions zero-emission balloon flights.
Porter's Five Forces Analysis of Aerospace Tourism
Rivalry is intense among established billionaires, while supplier power remains moderate due to specialized carbon-fiber and liquid-oxygen demands. High capital expenditure requirements create a formidable barrier to entry for new startups.
SWOT Analysis of the Commercial Space Sector
Strengths include cutting-edge reusable propulsion; weaknesses involve high passenger ticket costs. Opportunities lie in orbital manufacturing tourism, while threats encompass catastrophic launch anomalies and tightening international airspace regulations.
Value Chain Analysis: From Raw Materials to End-Users
The value flow begins with raw aerospace alloys and carbon fibers, moving through propulsion engineering by entities like SpaceX Starship Program Company, culminating in luxury astronaut training and orbital hospitality for end-users.
Investment Insights and High-Potential Areas
Investors should target life-support systems, orbital docking technology, and specialized training facilities managed by firms like Blue Abyss Ltd. These sub-sectors offer critical scalability as passenger flight frequency increases.
Conclusion and Strategic Takeaways
The Space Tourism Market transitions from experimental aviation to a multi-billion-dollar economic engine, validating the 8.44 Billion forecast by 2033 and rewarding early institutional investors who back robust safety systems.
Research Methodology and Baseline Triangulation
Our findings are derived from triangulating FAA launch license filings, executive interviews with stakeholders from companies like Space Adventures Inc, and macroeconomic indicators tracking ultra-high-net-worth wealth distribution.
Scope of the Report and Operational Parameters
This report evaluates commercial passenger spaceflight globally from 2026 to 2033. It excludes uncrewed scientific payloads and government-exclusive military space programs, focusing strictly on civilian and private astronaut expenditures.
Recent Developments and Industry Announcements
Recent strategic moves include partnerships between luxury travel brokers like SpaceVIP and infrastructure developers such as Vast Space LLC, signaling an accelerating race toward commercializing private low-Earth-orbit destinations.